





Global Softwood Supply Growth Set to Lag Demand Through 2035
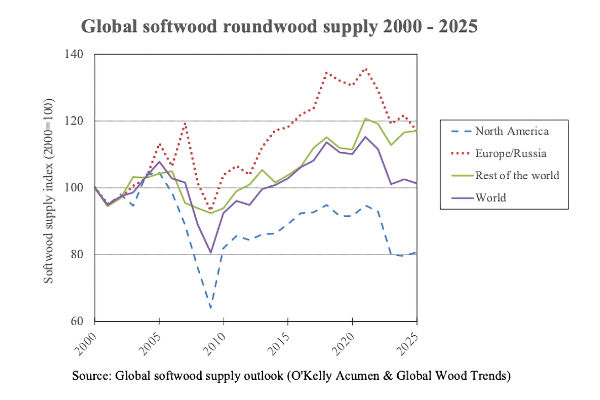
Global softwood markets are entering a period of tighter supply. Softwood roundwood supply has remained essentially flat since 2000 despite continued growth in overall roundwood production, and is forecast to increase by only about 0.5% annually through 2035. At the same time, demand for construction timber, packaging and biomass is expected to continue growing faster than supply. The result is a progressively tighter supply-demand balance, with increasing pressure on the availability and real prices of softwood logs. But the global picture masks major differences between regions.
Global softwood roundwood supply in 2025 was close to its 25-year average, following a dramatic decline from its all-time high in 2021. More importantly, the geography of supply has changed substantially since 2000. North American softwood roundwood supply has declined by almost 20%, while Europe/Russia and the rest of the world have each increased by about 18% (see chart).
These shifts are important because the regions that have contributed to global supply growth face very different prospects over the next decade.
Five regions, five very different supply stories
The US South offers the greatest opportunity for additional softwood roundwood supply. Timber resources are abundant, and harvests remain below biological growth. But labor shortages, infrastructure constraints, and the investment required to expand production will limit how quickly that potential can be realized.
Canada, after several years of declining harvests – particularly in British Columbia – is expected to stabilize and recover modestly. That recovery, however, is unlikely to restore the region to previous supply levels.
Europe faces considerably tighter constraints. Many forests are already being harvested close to sustainable biological limits, while sustainability policies, forest protection, and climate-related damage increasingly restrict further growth. The base scenario points to limited overall change, with declines in Central Europe and the Baltics offset by growth elsewhere, particularly in the Nordic region.
Russia has enormous, underutilized softwood potential, but potential does not necessarily translate into available supply. Political risk, restrictions on market access, infrastructure limitations, and investment requirements mean that much of the country’s resource is likely to remain untapped.
In Latin America and Asia-Pacific, plantation forestry remains competitive, but the softwood plantation area has changed little over the past decade. Investment in hardwood plantations has increased, while investment in softwood plantations has remained broadly unchanged. Productivity gains should support modest softwood supply growth, but not a major expansion in the region. In Japan and New Zealand, lower available supply is predominantly a result of uneven age-class structures.
These findings are drawn from the Global Softwood Roundwood Supply Outlook, a four-part market report series covering North America; Europe and Russia; Latin America, Asia and Oceania; and a global overview. Together, the reports examine where future softwood supply is likely to come from—and where supply growth is likely to be constrained.
The studies are conducted by Global Wood Trends (Seattle, US) and O’Kelly Acumen (Stockholm, Sweden).
More information and report details: Global Softwood Outlook
Source: Global Wood Trends
Back to NEWS:
BUSINESS l CLIMATE CHANGE l CONSTRUCTION l EDUCATION l ENVIRONMENT l FORESTRY ENGINEERING FORESTRY l GOVERNMENT l INTERNATIONAL l LAND l RECYCLING l RESEARCH l ROOFING l SHORT HAUL SILVICULTURE l SOCIAL RESPONSIBILITY l TRANSPORT l TREATMENT l TRANSPORT l VALUE ADDING
BUSINESS l CLIMATE CHANGE l CONSTRUCTION l EDUCATION l ENVIRONMENT l FORESTRY ENGINEERING FORESTRY l GOVERNMENT l INTERNATIONAL l LAND l RECYCLING l RESEARCH l ROOFING l SHORT HAUL SILVICULTURE l SOCIAL RESPONSIBILITY l TRANSPORT l TREATMENT l TRANSPORT l VALUE ADDING


